
ComplyAdvantage Alternatives: Replace It, or Add a Layer on Top
ComplyAdvantage alternatives compared: seven replacements for screening and monitoring data, plus Sphinx for working the alerts your provider produces.
TL;DR: The main Feedzai competitors are enterprise fraud suites (Featurespace, FICO Falcon, NICE Actimize, SAS, ACI), newer platforms that span fraud and AML (Hawk, Sardine), and the behavioral layer BioCatch. Ownership is the live story: Visa owns Featurespace and has agreed to buy BioCatch, and NICE is reported to be in talks to sell Actimize. Reported consumer fraud losses reached about $16 billion in 2025, according to the FTC, which is why scoring choices get revisited.
Sphinx wrote this list, using vendor material, filings and press, and the numbers are an order of fit for a team replacing Feedzai's real-time fraud scoring, not a quality ranking.
Sphinx is not on the numbered list. It does not score transactions in real time, so it is not a Feedzai competitor in the sense most buyers mean.
Feedzai is a RiskOps platform that scores payments and customer events for fraud and supports AML work on the same system. The company says it risk-assesses $19 trillion in payments a year across 140 billion events. In the past 18 months it has announced RiskFM, a foundation model trained on financial data, added transaction screening through a partnership with Neterium, and launched Farol, an AI agent embedded in its analyst workflow. It raised about $75 million at a valuation above $2 billion in October 2025 and remains independent, and it reported being first-ranked tenderer in a European Central Bank framework agreement for digital euro fraud prevention.
None of that suggests a product in trouble. Teams search for Feedzai alternatives for more ordinary reasons. A contract is up for renewal and procurement wants a real comparison. A card-heavy issuer wants to weigh consortium models against behavioral ones. A smaller institution wants a lighter deployment. A bank on one vendor's payments stack wants fraud from the same place. Fraud pressure adds to this: the FTC reported about $16 billion in consumer fraud losses for 2025, the highest on record and about 25% above 2024. Our wider comparison of fraud detection platforms covers the category beyond this one vendor.
Featurespace vs Feedzai is mostly a question of model philosophy and ownership. Featurespace built its name on Adaptive Behavioral Analytics, which profiles each customer's genuine behavior and flags departures from it. Feedzai now describes itself around a broader lifecycle, from onboarding through payments and AML, and around pooled intelligence delivered through its own models and scores.
The ownership gap is plainer. Visa completed its purchase of Featurespace in December 2024, and the business sits in Visa's Risk and Identity Solutions unit. Feedzai is an independent company. Some buyers will read a network owner as reach and distribution. Others will prefer a vendor with no card network above it. Both are reasonable positions, and neither says anything about detection quality, which only a test on your own data can settle.
Entries near the top are closer like-for-like replacements for Feedzai's scoring. Entries lower down cover part of the job, or suit a narrower buyer.
Featurespace, now sold as a Visa solution, monitors customer activity in real time using Adaptive Behavioral Analytics and Automated Deep Behavioral Networks. Its platform, including ARIC Risk Hub, covers card, payment, application and merchant acquiring fraud, plus financial crime detection, and feeds analyst decisions back into its models. Visa says its enhanced A2A Protect, launched in September 2026, carries a unified fraud score and is the first in-market integration of Featurespace technology. It suits institutions that want the closest functional match to Feedzai and like a customer-behavior approach. The honest limit comes from the ownership: the roadmap now sits inside a card network, so buyers with heavy non-Visa volumes should ask how product priorities are set.
FICO Falcon Fraud Manager scores transactions for fraud risk, with a direct link to authorization systems so a payment can be declined at the point of sale. FICO says Falcon protects more than 4 billion payment cards, and that its models train on tagged transactions from a consortium of more than 10,000 financial institutions. FICO has since added scam detection models and a wider Enterprise Fraud Solution on FICO Platform. It suits issuers and processors that value a long-running card model and shared data. The limit follows from how consortium models work: they learn from pooled history, so a portfolio that looks unlike the pool should test performance on its own data before relying on the score.
NICE Actimize's IFM platform covers payments fraud, scams and mule activity, new account fraud, authentication and investigations, with a separate Xceed offering for small and mid-sized banks. It suits large institutions that want many fraud use cases and their investigation tooling from one vendor. Ownership is the open question. CTech, citing Sky News, reported in September 2026 that Brookfield was in exclusive talks to buy Actimize from NICE for about $2 billion, and cautioned that the deal could still fall apart. We found no announced agreement as of late October. The limit for a new buyer is that uncertainty, so ask about change-of-control terms and roadmap commitments before signing a multi-year contract.
SAS Fraud Decisioning is a cloud-native product on SAS Viya covering payment, account takeover, application, synthetic identity, check and digital fraud. It includes prebuilt models, model governance, alert triage and case management, and SAS supports a combined fraud and AML approach across its financial crime products. SAS remains private, held by its two co-founders. It suits institutions with analytics teams that want control over models and already work in the SAS environment. The limit comes from the architecture: adopting the product means adopting SAS Viya, which is a larger decision for a team that only wants a fraud score through an API.
ACI Worldwide sells fraud management for financial institutions as a service, in public cloud or on premises, using what it calls incremental machine learning. ACI Fraud Scoring Services delivers a score with an explanation through API calls, and is designed to complement existing fraud tools. ACI Connetic, its cloud-native platform, brings account-to-account payments, card payments and fraud prevention onto one architecture. It suits banks that already process payments on ACI or are considering it. The limit is the flip side of that pitch: a bank on another payments stack gets less from the unified architecture and should judge the fraud product on its own.
Hawk offers modular AML, screening and fraud products on one platform, with real-time fraud decisions it puts at 150 milliseconds on average, self-serve rule management and check fraud coverage. It also lists investigative and screening agents. The company raised a $56 million Series C in April 2025 and reported more than 80 customers at the time, from large banks to fintechs. It suits institutions consolidating fraud and AML vendors. The limit is scale of evidence: that customer count is a smaller reference pool than older vendors on this list, so ask for references that match your size and payment mix.
Sardine positions itself as a risk platform unifying fraud prevention, AML and transaction monitoring for banks, merchants and fintechs. It evaluates payments before funds move across ACH, wires, SEPA, RTP, FedNow, Zelle and checks, using behavioral, device and network signals, and it offers Sardine Flow for building workflows that connect data, rules and AI agents. It suits digital-first institutions where payments are irreversible within seconds. The limit comes from its breadth: much of the value assumes consolidation, so a large bank locked into separate fraud and AML contracts may only be able to use part of it at first.
BioCatch analyzes application, behavioral, device and network signals, such as keystrokes and touch gestures, to separate real users from fraudsters and coerced customers during a digital session. Products cover account opening, account takeover, mule accounts and scams. CNBC reported in August 2026 that Visa will buy it for $2.4 billion in cash from Permira and other investors, with closing expected by the end of Visa's fiscal second quarter of 2027, subject to regulatory approvals. If it closes, Visa will own two names on this list. BioCatch comes last because it is more often an addition than a substitute. Its signals come from digital sessions, and it describes itself as working alongside existing controls, so it does not replace a transaction decisioning engine on its own.
Sphinx works on the investigation that follows a fraud or AML alert, whichever system raised it. Every platform above produces alerts, and someone still has to pull the transaction history, check the counterparties, run the KYC or KYB checks, write the case note and reach a view. Sphinx's AI analysts log into the tools a team already uses, prepare the evidence, apply your SOPs and produce a traceable recommendation. Your team retains final approval.
That makes Sphinx an addition, not a replacement. It will not block a payment or generate a score, so a team that needs real-time decisioning needs one of the vendors above. For teams already on Actimize, Hawk or Sardine, the useful question may be whether to replace the tool or add an investigation layer on top. Several of these vendors are building investigation agents of their own, so compare what each does in your workflow. The Sphinx median case takes 3.2 minutes, with 94-98% agreement with analysts, and Sphinx's AI agents took Alviere from 14 to 2.4 minutes per case. Teams merging the two functions may also want our explainer on FRAML and fraud-AML convergence.
Start with where the loss or the workload actually sits. A team losing money to scams on instant rails has a different problem from one with a false alert queue it cannot clear, and a new scoring engine only addresses the first. If you are replacing a scoring engine, these questions separate the options quickly:
Scoring gets the attention in a vendor evaluation, but the second half of the process is where the review hours go. A bank's SAR deadline, under FinCEN's rule, is generally 30 calendar days from initial detection of facts that may support a filing, and no detection engine files that report for you.
The closest competitors for real-time fraud scoring are Featurespace, FICO Falcon Fraud Manager, NICE Actimize, SAS Fraud Decisioning and ACI Fraud Management. Hawk and Sardine compete with platforms that span fraud and AML. BioCatch overlaps on scams and account takeover, though it usually sits alongside a decisioning engine.
Visa completed its acquisition of Featurespace in December 2024. It signed a definitive agreement to buy BioCatch for $2.4 billion in August 2026, and that deal remains subject to regulatory approvals, with closing expected by the end of Visa's fiscal second quarter of 2027.
Press reports say NICE has been running a sale process, and Sky News reported in September 2026 that Brookfield was in exclusive talks at about $2 billion. Neither company had announced a signed deal as of late October 2026, so treat the buyer and price as unconfirmed.
No. Sphinx does not score transactions in real time or decide whether a payment clears. It handles the investigation work after a fraud or AML alert, and it runs alongside a detection platform. Pricing is a platform fee plus usage tiers scoped to your volumes.
We found no public rate card on the vendor pages we read for this list. Featurespace's AWS Marketplace listing says standard pricing is per transaction, with custom pricing by private offer. Expect pricing to depend on volumes and scope, and get it in writing during the evaluation.
ComplyAdvantage alternatives compared: seven replacements for screening and monitoring data, plus Sphinx for working the alerts your provider produces.
Comparing NICE Actimize alternatives? See when to replace it, when a layer on top fits better, and what cost and migration risk to weigh.
Outsourced vs in-house AML compliance compared: in-house teams, BPOs, AI agents, and hybrids. Regulators say accountability never leaves the bank.
How to run an AML investigation: intake, L1 triage, L2 escalation, evidence, 314(b), typology analysis, the SAR decision, QA, and continuing review.
12 AML compliance KPIs every BSA team should track, from alert-to-SAR conversion and SAR timeliness to QA defect rate and cost per alert.
A Secretary of State search proves an entity exists and its status, not who owns it. What each state shows, good standing, agents, and BOI.
A 12-step AML checklist for switching compliance platforms: exit terms, 5-year BSA record retention, validation, parallel runs, and cutover.
25 questions to ask AML software vendors in an RFP, grouped by detection, explainability, model risk, data, security, pricing, and proof.
How to verify foreign businesses: registry access by jurisdiction, non-Latin names, UBO thresholds, apostilles, FATF lists, and a coverage test.
A risk-based approach to AML identifies, assesses, and mitigates illicit finance risk in proportion to that risk. It is not the written assessment.
A bank files a SAR within 30 days of initial detection, or 60 days if no suspect was identified that day.
Payment screening compares a wire, ACH, or SWIFT message with sanctions lists before funds move. It is separate from customer name screening.
Source of funds traces a transfer. Source of wealth traces how net worth was built. When each is required, and what evidence holds.
Automate CIP, screening, UBO resolution, risk rating, and the evidence pack. Source of wealth, high-risk approval, and SAR suspicion stay with a person.
Best compliance software for credit unions has to cover BSA/AML, sanctions, KYC, shared branching, and examiner-ready case files.
What a bank sanctions screening program must include: lists, customer and payment screening, escalation, and examiner records.
How to cut false alerts in transaction monitoring by tuning one scenario at a time, fixing data, and keeping the threshold version.
How to compare UBO mapping tools when a U.S. registry does not return owners: chains, the 25 percent prong, and the control person.
How to set lists, match thresholds, disposition paths, and testing for automated sanctions screening alerts.
What a KYB API returns from a U.S. registry, what it does not, and why banks still collect beneficial owners under CDD.
How compliance teams build, tune, and document transaction monitoring: risk-based scenarios, data quality, and alert decisions.
What to evaluate in AI screening alert tools: triage, false-positive claims, OFAC calibration, and an audit trail you can replay.
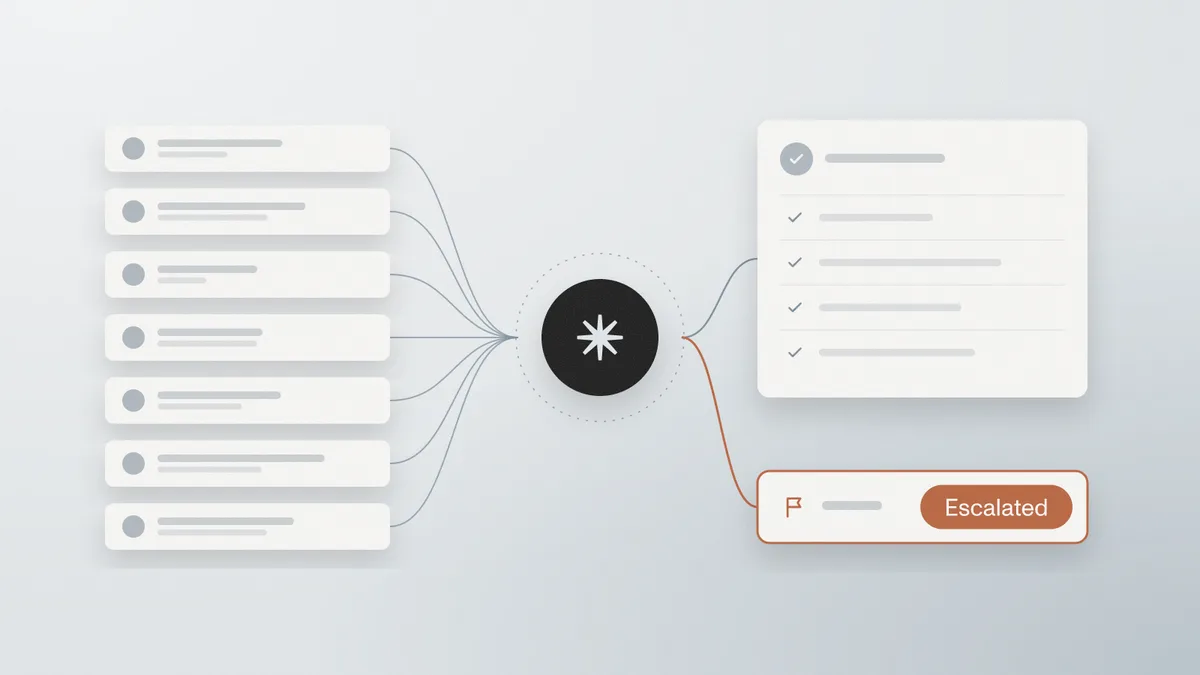
What breaks a compliance platform at high alert volume: queue age, rule noise, analyst minutes, and audit reconstruction.
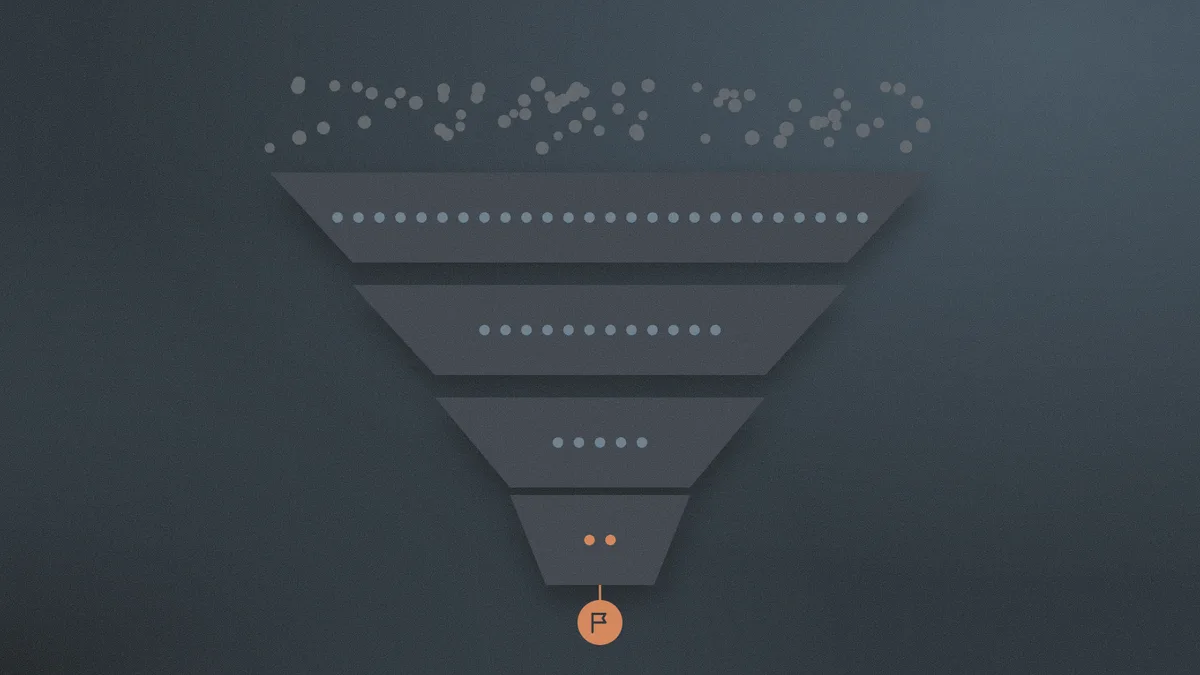
Manual KYB cost covers analyst time, rework, lost onboardings, missed owners, and later audit reconstruction. Corporate reviews average $2,274.
Small fintechs need a full KYB file: entity, owners, control person, refresh, and an audit trail. Cheap checks skip the hard parts.
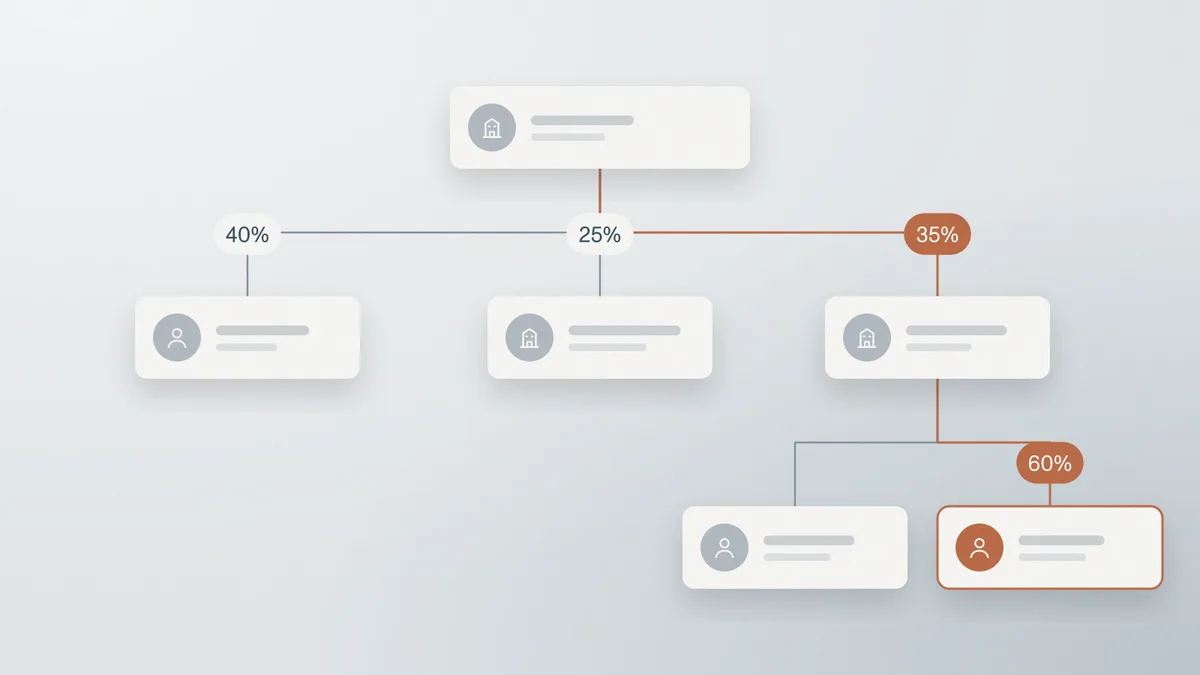
AML screening is slow because each hit is research: list updates, fuzzy names, weak aliases, missing context, and a written disposition.
What payment processors and payfacs should demand from KYB: sub-merchant underwriting, ownership, and monitoring after the business changes.
KYC false positives start in the name match. FCA tests found 75% detection on slight variants. How list scope and date of birth clear the rest.
What a BSA program must operate: CIP, CDD, SAR and CTR filings, sanctions screening, and risk-based controls.
How to backtest AML rules on historical data, run shadow mode and champion-challenger in production, and document results for model risk management.
How entity resolution and graph analytics identify beneficial owners: probabilistic matching, blocking, indirect ownership math, cycles, registry limits.
Integration patterns, data mapping, cutoffs, sandbox and UAT, reconciliation, and post-go-live failures when connecting AML and KYC tools to a bank core.
Compliance orchestration routes data, decisions, and cases across KYC, KYB, sanctions, and monitoring tools. Architecture patterns and what to evaluate.
Senate PSI report: 84% of Iran-linked sanctioned wallets ran on USDT. Why a post-designation freeze is not a sanctions program, and what regulators ask.
Brazil's betting ban pushes 30M bettors to illegal sites. What Pix monitoring teams will see, SPA Ordinance 2,750's red flags, and why alert queues flood.
MP 1,394 article by article: CPF refund lists, the 7-day bank restitution window, SPA reporting, Caixa fallback, and the pending Central Bank Pix block.
Who counts as an MSB, FinCEN Form 107 registration, state licensing, the $2,000 SAR threshold, agent oversight, and what IRS BSA examiners find.
The OFAC SDN List names blocked persons, vessels, aircraft, and crypto addresses. How screening works, what a true hit requires, and what a miss costs.
What the crypto Travel Rule requires of VASPs: FATF R.16, FinCEN's $3,000 rule, EU and UK thresholds, self-hosted wallets, IVMS 101, and the sunrise gap.
How bust-out fraud works, how it differs from default and account takeover, the signals and features that catch it, and why the loss ends up as a SAR.
How to run an enterprise BSA/AML risk assessment: FFIEC categories, inherent vs. residual risk, refresh triggers, examiner criticisms, program linkage.
How fuzzy name matching works in sanctions screening: Levenshtein, Jaro-Winkler, phonetic keys, OFAC's own scorer, threshold trade-offs, and validation.
Placement, layering, and integration: the techniques, transaction-data signatures, and controls at each stage, and why real schemes break the model.
CIP is the BSA identity program at account opening under 31 CFR 1020.220.
A Currency Transaction Report is FinCEN Form 112 for cash over $10,000 in one business day. Covers aggregation, exemptions, and how CTRs differ from SARs.
What FinCEN 314(a) information sharing is: government-to-institution searches, 14-day match reporting, and how it differs from voluntary 314(b).
BSA officer responsibilities go beyond a board title: designation, independence, SAR authority, board reporting, staffing, and what examiners test.
Wire fraud detection for banks: known-number callbacks, beneficiary checks, mule holds, and 24-hour IC3 recall. IC3 reported $20.877B in 2025 losses.
BSA independent testing: independence, risk-based frequency, sampling, board reporting, and what OCC examiners expect after Bulletin 2025-37.
How banks evaluate AML vendors under OCC and FFIEC third-party risk rules, including residual BSA risk for processors, screening, BPO, and model vendors.
How banks and credit unions detect altered, counterfeit, forged, and duplicate checks: typologies, detection layers, Reg CC holds, and SAR key terms.
What an AML lookback review is, what triggers one, how regulators scope it, what TD Bank-scale lookbacks cost, and how automation changes the economics.
Shell company red flags at onboarding and in transaction activity, how to investigate a suspected shell, and what detection tooling needs to do.
The five pillars of an AML compliance program, what examiners test under each, common exam findings, and how FinCEN's 2026 proposed rule reframes them.
How transaction monitoring rule tuning works: ATL/BTL testing, sensitivity analysis, segmentation, cadence, and the documentation examiners expect.
How banks detect account takeover fraud: attack vectors, the signals that give ATO away, SAR and FFIEC obligations, and how to evaluate detection tools.
Customer risk rating in AML: the five factors behind the score, static vs dynamic rating, how scores drive EDD and monitoring, and what examiners expect.
FinCEN human trafficking red flags for banks: labor vs sex trafficking footprints, funnel accounts, payroll absences, SAR filing rules, and forced criminality typologies.
How FinCEN 314(b) information sharing works after the June 2026 fact sheet: safe harbor conditions, fraud coverage, real-time sharing, enrollment, and the renewal trap.
APP fraud prevention across UK, EU and US rules: what Confirmation of Payee fixes, what it cannot, and why receiving-side mule detection only got built when liability shifted.
What the GENIUS Act requires of stablecoin issuers: reserves, BSA program, seize and freeze capability, Travel Rule, MiCA comparison, and the secondary market gap.
Why synthetic identities pass CIP, how the credit bust-out lifecycle works, which signals actually detect them, and why the risk concentrates in super prime.
How to build an AML QA program: sampling design, scorecards, error taxonomy, 2026 enforcement actions, and what changes when AI agents disposition alerts.
How banks detect pig butchering scams: FinCEN red flags, the trial-transaction signal, receiving-side mule controls, and why 78% of victims defend the payment.
Eight financial crime, compliance and fintech conferences in fall 2026. Dates, cost, audience, date conflicts and which deserves your travel budget.
ACAMS Assembly Las Vegas 2026 runs Sept 29-Oct 1 at ARIA. Theme, agenda, 15 credits, the free CAMS seminar most attendees miss, and how to prepare.
XLoD Global New York 2026 runs Sept 24 at the Javits Center. Streams, speakers, who attends, how to prepare and what to ask vendors.
Money20/20 USA 2026 runs Oct 18-21 at The Venetian, Las Vegas. Content pillars, costs, schedule, who it suits and how to prepare.
FinovateFall 2026 runs Sept 9-11 at the Marriott Marquis Times Square, NYC. Demo format, agenda, compliance sessions, costs and how to prepare.
Global Anti-Scam Summit America 2026 runs Sept 2-3 at Pier 48, San Francisco. Dates, ticket tiers, agenda focus areas, who attends and how to prepare.
Stablecon 2026 runs Sept 9-11 at National Harbor, Maryland. Dates, venue, agenda, GENIUS Act context, who attends and how to prepare.
Elder financial exploitation detection separates elder scams from theft by trusted persons. FinCEN SAR rules, red flags, and how to evaluate a program.
Sanctions evasion red flags across six typologies: front companies, ownership obfuscation, transshipment, AIS manipulation, and trade misdescription.
Structuring in banking explained: 31 U.S.C. 5324, the $10,000 CTR threshold, red flags, SAR obligations, and how to build defensible detection.
How sponsor banks supervise fintech and BaaS partners: third-party risk expectations, who owns BSA/AML, ledger access, and oversight cadence.
How correspondent banks assess respondent institutions: FATF Rec 13, the Wolfsberg CBDDQ, nested accounts and Section 312 enhanced due diligence.
Trade-based money laundering moves criminal value through misinvoiced trade. The core techniques, red flags in trade finance, and how to build controls.
What AML model validation requires after SR 26-2 replaced SR 11-7: scope, threshold tuning, outcomes analysis, and the evidence examiners expect.
Compare API-first compliance platforms that embed screening, monitoring, and verification into product workflows. Covers latency, pricing, and integration patterns.
Compare business onboarding software for banks, credit unions, and fintechs. Covers KYB verification, UBO mapping, screening, and risk-based due diligence workflows.
Head-to-head comparison of transaction monitoring software pricing models, key features, and ROI drivers for banks and fintechs in 2026.
How banks detect fraud in real time using rules, behavioral analytics, and network intelligence. Covers detection architecture, false positive management, and regulatory expectations.
Compare compliance automation platforms for fintechs: financial crime compliance (AML, KYC) and security compliance (SOC 2, ISO 27001). Evaluation criteria and pricing.
Compare the best financial crime prevention software for banks and fintechs in 2026. Covers unified platforms, AI-native challengers, and key evaluation criteria.
Compare KYB platforms for regulated financial institutions including LexisNexis, Middesk, Alloy, Trulioo, GBG, and Sumsub with audit trail and compliance evaluation criteria.
A practical guide to automating AML and KYC compliance processes covering alert triage, screening, onboarding, and SAR filing with evaluation criteria and common pitfalls.
Compare the top KYB automation platforms for fintech in 2026. Covers Middesk, Sumsub, Alloy, Persona, Trulioo, and more with pricing, coverage, and evaluation criteria.
Five practical strategies to cut business verification time including parallel checks, API-first data, automated UBO traversal, risk-based routing, and perpetual monitoring.
How the OFAC 50 Percent Rule works, including indirect ownership, aggregation across sanctioned owners, and documenting screening decisions.
A mule account moves fraud proceeds through the banking system. Learn the detection signals, analyst investigation steps, and SAR reporting requirements.
Credit unions face document fraud at three unique entry points: member onboarding, indirect lending, and shared branching. How to evaluate detection at credit union scale.
AI-generated document fraud is surging. Most onboarding platforms rely on OCR and template matching that miss synthetic forgeries. How multi-layer verification catches what legacy checks cannot.
A guide to the four types of document fraud in banking and the five-layer detection framework compliance teams need to catch AI-generated fakes.
Community banks face the same BSA/AML requirements as institutions 10x their size. Learn what to look for in AML technology, how FinCEN's effectiveness rule changes the game, and how to evaluate solutions for $1B-$10B institutions.
What BSA examiners evaluate at community banks in 2026: risk assessment currency, TM tuning rationale, SAR narrative quality, CDD documentation, and how AI audit trails change the exam conversation.
Ranked comparison of the top crypto compliance software in 2026 covering Chainalysis, TRM Labs, Elliptic, ComplyAdvantage, Crystal Intelligence, Merkle Science, Notabene, and Sphinx.
UBO mapping automation replaces manual ownership tracing with systems that reconstruct corporate ownership graphs programmatically. Learn how to evaluate tools.
Ranked comparison of the best SAR filing software in 2026 covering Hummingbird, Abrigo, NICE Actimize, Verafin, Lucinity, Unit21, Flagright, and Sphinx.
Ranked comparison of the best transaction monitoring software in 2026 covering NICE Actimize, SAS, Feedzai, Hawk AI, ComplyAdvantage, Verafin, Unit21, Quantexa, and Sphinx.
Ranked comparison of the best sanctions screening software in 2026 covering Dow Jones, Refinitiv, ComplyAdvantage, NICE Actimize, LexisNexis, Napier AI, Alessa, and Sphinx.
PEP screening identifies politically exposed persons, their family members, and close associates to apply risk-based enhanced due diligence under FATF and AML regulations.
Adverse media screening searches public sources for risk signals about customers. Learn what regulators require and how to evaluate a screening program.
Ranked guide to the best compliance case management software in 2026. Covers evaluation criteria, platform categories, regulatory requirements, and how to choose.
Financial crime detection identifies suspicious activity after the fact. Prevention stops it before funds move. Here is how to evaluate the right balance for your compliance program.
Evaluate business onboarding automation software for banks. Covers KYB verification, beneficial ownership, sanctions screening, and what to look for in a platform.
What banks must verify, monitor, and document under FinCEN's CDD Rule — including the 2026 beneficial ownership changes and how to evaluate your program.
Compare risk assessment software for banks and fintechs. Covers AML risk scoring, regulatory alignment, audit trails, and what compliance teams should evaluate.
Modern fraud detection layers ML scoring, behavioral biometrics, and graph neural networks to catch fraud in milliseconds while reducing false positives.
Perpetual KYC (pKYC) replaces periodic reviews with continuous, event-driven monitoring. Learn how it works, what triggers reviews, and what it takes to implement.
Compliance officer burnout is a systems problem, not a people problem. Learn how AI case-level automation removes repetitive volume and makes the role sustainable.
The AML efficiency gap separates compliance activity from risk reduction. Learn how outcome-based measurement and lower false positive rates close it.
Learn how to write SAR narratives that law enforcement can act on. Covers FinCEN's five-W framework, October 2025 guidance changes, and common mistakes to avoid.
FRAML merges fraud and AML into one program. Learn why 93% of mid-market banks are converging, the cost savings, and how to evaluate readiness.
FinCEN's 2026 proposed rule replaces process-driven AML compliance with an effectiveness-based standard. Learn the two-pronged framework and how to prepare.
Ranked comparison of the best fraud detection platforms in 2026 covering Feedzai, NICE Actimize, Featurespace, SAS, and Hawk AI with an evaluation framework.
Ranked guide to the best compliance software for financial services in 2026, covering AML, KYC, KYB, and security compliance platforms.
UBO identification traces beneficial ownership through corporate layers to find the natural persons who own or control an entity.
Ranked comparison of the best AML software in 2026 covering ComplyAdvantage, NICE Actimize, LexisNexis, Hawk AI, TRM Labs, Alloy, and Sphinx.
Screening alerts take 30-45 minutes each, with 85-90% being false positives. Four capabilities cut review time without compromising audit readiness.
Enhanced Due Diligence (EDD) applies deeper scrutiny to high-risk customers. Covers triggers, requirements, source of funds verification, and the operational cost of EDD programs.
KYB (Know Your Business) verifies business entities, ownership structures, and beneficial owners. Guide covering FinCEN CDD Rule, FATF Rec 24, and evaluation criteria.
KYC verifies individuals, KYB verifies business entities and their beneficial owners. A comparison of scope, complexity, cost, and regulatory drivers.
Screening alert backlogs are a design problem, not a staffing problem. Most systems were built to flag matches, never to resolve them at scale.
AML transaction monitoring detects suspicious financial activity through rules and behavioral models. Covers detection methods, alert investigation, SAR filing, and false positives.
U.S. crypto AML compliance: regulators are no longer satisfied with policy documents. They want evidence that the program actually ran.
Compare the best KYC software in 2026. See top vendors, key strengths, and the compliance gaps buyers should evaluate before choosing.
Learn what actually reduces AML false positives - data quality, context, explainability, and automation - and how to spot vendor theater.
Global compliance automation that scales seamlessly across borders.
Try another keyword or explore a different topic.