
How to Tell if a PDF Has Been Edited: Six Things to Inspect
How to tell if a PDF has been edited using document properties, dates, producer fields, saves, signatures, and fonts, and why each can mislead.
TL;DR: A fake receipt is proof of purchase that was edited after a real transaction or generated for a purchase that never happened. AppZen platform data reported by Accounting Today shows AI-generated images rising from 0% to 70.8% of the fake receipts it flagged between March 2025 and mid-May 2026, which describes one vendor's flagged files and not overall prevalence. Visual review cannot settle a receipt, so the deciding test is a match against card data or the merchant's own records.
A fake receipt is a record of a purchase that did not happen as shown. Reviewers meet it in expense reports, insurance claims for lost or damaged goods, retail returns, benefit reimbursements, and loan files that take proof of purchase. The document fails in the same two ways in each queue.
Edited-after-creation starts from a genuine receipt and changes the amount, the date, the merchant, or the items. Generated-from-scratch describes a transaction with nothing behind it. Emburse's 2026 survey, fielded by Atomik Research, split its U.S. respondents along similar lines: 19% had used AI to fabricate a purchase, 15% to inflate the value of something they bought, and 6% to replace a lost receipt for a genuine purchase. That last group matters for policy. A recreated receipt is a false document even when the expense was real, and a written rule should say how the team treats it.
A useful baseline for what a receipt must show comes from tax substantiation. IRS Publication 463 says documentary evidence is ordinarily adequate if it shows the amount, date, place, and essential character of the expense. The same publication generally does not require documentary evidence for non-lodging expenses under $75, and an employer's policy can be stricter. Those four elements work as a presence check in any queue. A receipt that carries all four can still be fake.
Accounting Today reported that AppZen's 70.8% figure rests on 1,471 AI-generated fake receipts from 745 employees at 174 companies, claiming $148,143 in total. Those receipts averaged about $100, with a median near $32. Fakes built from older templates averaged $182. The article is careful on one point: the figure shows the share of flagged fakes that were AI-generated, and it does not measure how much fraud grew.
The same report covers Emburse's poll of 2,000 U.S. and U.K. workers, where 34% said they had used AI to generate a fake receipt for a business expense, including 40% of U.S. respondents. Both datasets come from companies that sell expense software, and the survey is self-reported, so they show direction better than prevalence.
Independent casework explains why small claims deserve attention. The ACFE's Occupational Fraud 2026 report found expense reimbursement schemes in 13% of the 2,402 cases studied, with a $36,000 median loss and a median of 18 months before detection, against 12 months across all cases. A review program that only examines claims above a dollar line will rarely see a $32 receipt. Random sampling below the line closes that gap.
A digital receipt and a photographed receipt are different evidence. An e-receipt or order confirmation exported as a PDF carries a production history: the software that wrote it, a text layer, and timestamps. A reviewer can ask whether that history fits a merchant's system. A photo or screenshot is only pixels. Camera metadata may be absent after messaging or upload, so the file often says little about its origin.
Paper receipts reach the queue as photos, and that is ordinary. Missing metadata on a phone image is not a finding. The harder consequence is that a generated receipt and a genuine photo arrive in the same container, because an image model and a camera both output pixels. What flattening discards applies here in full: an image-only file supports fewer checks, so the conclusion should carry less weight.
What survives on an image is still useful: the arithmetic, the type across lines, compression around an altered region, and whether the image appears on another claim. Where a merchant issues digital copies, a reasonable policy asks for one above a materiality line.
Three tells keep working because they test the transaction instead of the page.
Merchant identity asks whether this business exists, operates where the receipt says, and sells what the receipt lists. A business registry or the merchant's own site, found independently, can answer that. Trade names, parent companies, and payment processors make names differ legitimately, so a mismatch calls for a question and does not end the review.
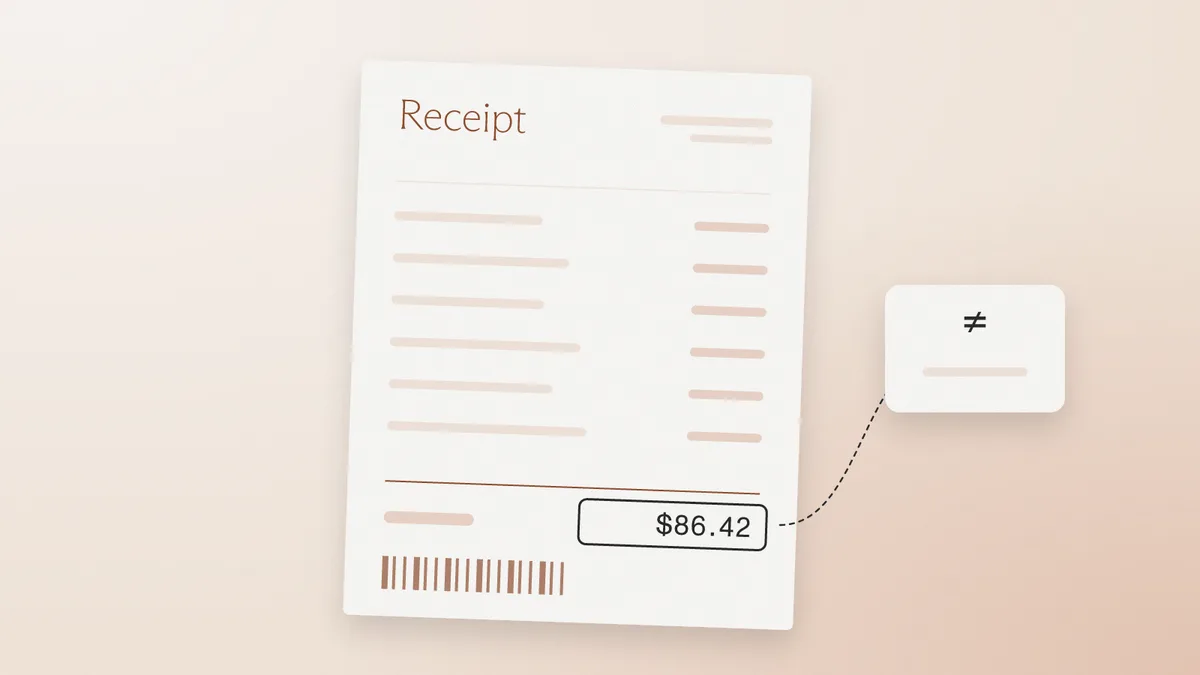
Tax arithmetic asks whether the subtotal, tax, and total agree, and whether the tax is plausible for the place of sale. Exempt items, mixed-rate baskets, and rounding all produce honest variation. A total that cannot be rebuilt is a real finding. A total that rebuilds proves little, since a generated receipt can be composed so that its lines agree.
Timing against card data asks whether the receipt's date, amount, and merchant line up with a card authorization. Posting dates lag, and tips can change a restaurant total after the receipt prints, so small differences have innocent explanations. A receipt with no matching transaction at all is the strongest of the three signals.
The receipt's story is that this merchant recorded this sale, for this amount, at this time. Six classes of signal test whether the file supports it.
Production method asks how the file was made: a merchant export, a later edit of that export, or an image with no document underneath. Timestamp trail asks whether creation and modification fit the claimed purchase date, and a file created days after the claimed sale needs a reason. Issuer matching asks whether the file resembles what this merchant's systems would produce.
Consistency tests the numbers and the type against each other. Model artifacts are the rendering traces that generation leaves in an image. Recycled patterns look across files, because one reviewer holding one receipt will never see its twin in another team's queue. Serial reuse detection needs that wider view. On a photo, the first two signals may have little to read.
File forensics can show that a document was altered. No inspection of a file can prove a purchase took place. That proof comes from a record the submitter did not produce.
A card feed match is the most direct source. A corporate card program gives the reviewer the transaction without asking the employee for anything. On a personal card, a statement line helps, though the statement is itself a document under test. Cash purchases have no feed, so they lean on merchant records and deserve closer sampling.
Merchant records answer the question directly. A returns desk can look up its own point-of-sale system. An insurer can contact the merchant with the transaction number, using contact details the insurer found independently and not those printed on the receipt. A lender financing equipment can confirm the sale with the vendor, the same discipline described in how to spot a fake invoice. Small merchants may hold no searchable record, and a failed lookup alone proves nothing.
Each confirmation has limits. A card match shows payment. It cannot show a business purpose, and it does not reveal a later refund. In an insurance claim, a confirmed purchase establishes that the item was bought and leaves the loss itself to be investigated.
Hold the claim before paying it. Redo the arithmetic, then check the merchant and the card record. If the claim rests on an image, ask for the digital original or a statement line. Treat a request for more evidence as routine, because honest claimants lose paper receipts.
Record which class the concern falls into, edited or generated, and what evidence supports it. When the numbers agree and the file still looks wrong, check the file for a scored read of its production history, then return to the card feed or the merchant for the outside answer. Route confirmed cases to HR, the SIU, or the fraud team under the existing policy, and apply that policy the same way to every submitter.
Sphinx examines the file and shows a reviewer why it scored the way it did, across the six checks above. Sphinx's published figures are a 94.3% correct verdict and under 28 seconds to clear clean files, at $0.45 per document with no seats or platform fee. Sphinx does not connect to bank accounts, so the transaction match stays with the team's expense or claims system, and the team keeps final approval. The free playground covers 50 documents with no card.
Rebuild the subtotal, tax, and total, confirm the merchant exists and sells the item, and match the date and amount to a card transaction or the merchant's own record. Print quality and fonts are weak signals, since genuine receipts fade and competent fakes look clean.
Often, though certainty from the image alone is rare. Model artifacts and reuse across claims can flag a generated receipt, while an image-only file offers less to examine than a merchant's original PDF. A receipt with no matching card transaction or merchant record is stronger evidence than any visual cue.
Many expense policies accept photos, and paper receipts usually arrive that way. A photo supports fewer forensic checks than a digital original, so higher-value claims benefit from a card match or a digital copy from the merchant. IRS Publication 463 treats documentary evidence as ordinarily adequate when it shows amount, date, place, and essential character.
A card match shows that a payment of that amount reached that merchant. It does not show what was bought, whether the purchase had a business purpose, or whether it was later refunded. The receipt can still be edited on line items even when the total matches the card.
How to tell if a PDF has been edited using document properties, dates, producer fields, saves, signatures, and fonts, and why each can mislead.
How to spot a fake proof of address across utility bills, leases, and statements, and what US CIP actually requires for an address.
How lenders, landlords and underwriters spot fake proof of income: test whether the documents agree, then confirm the figure at a source.
What a fake document checker can tell from a file, how to read its verdict and score, and what to check before uploading sensitive documents.
Fake documents grouped by the fraud they enable: income, banking, corporate and tax. 20 file types, each one's strongest tell, and a full guide.
Eight AI-generated document detection tools compared by fit, what each reads, and its limits, plus why no detector catches every forged file.
Bank statement fraud detection software compared for lenders and KYB teams: file forensics, statement analysis, and when a bank connection wins.
Eight document verification tools for banks, lenders and fintechs, sorted by job: identity documents, income files, and whether a file was altered.
Resistant AI alternatives for document forensics and transaction monitoring, ordered by fit, with what each does and where it stops.
Six Inscribe alternatives, sorted by what a buyer needs: work after the flag, document mix, data terms, pricing and how edits get caught.
Eight document fraud detection tools compared by what they test, how they explain a verdict and how they price.
How to spot a fake letter of credit or SBLC: why a standalone PDF is a red flag, tells that still work, and six checks on the file.
How to spot a fake gift letter: disguised loans, interested-party money, and how to verify the donor's transfer against Fannie Mae and FHA rules.
How to spot a fake payoff letter: altered wiring instructions, the tells that fail, and six checks on the file before the payoff wire goes out.
How to spot a fake certificate of trust: edited trustee names and powers, notary checks, beneficial ownership, and six checks on the file.
How to spot a fake shareholder register: edited percentages under the 25% UBO line, cap tables vs. registers, and the checks that catch them.
How to spot a fake crypto exchange statement: edited PDFs, CSV exports, on-chain withdrawal checks, and six checks on the file.
How to spot a fake credit card statement used for proof of address, debt verification, or source of funds: edited balances, broken math, file checks.
Spot a fake W-8BEN by reading foreign status, the treaty claim, and the file. The IRS publishes a blank and does not certify the form.
How to spot a fake partnership agreement: edited partner lists, signature blocks never executed together, and no state filing for a general partnership.
How to spot fake corporate bylaws: rules that contradict the articles, adoption before incorporation, and a template reused across companies.
How to spot a fake stock certificate offered as KYB ownership evidence, when the ledger matters more than the vignette.
A Schedule K-1 reports a partner's share of income. Capital-account math, form year, and an IRS transcript catch edited and generated fakes.
A fake 1099 is an information return edited after creation or generated from scratch. Match it to the IRS wage and income transcript.
How to spot a fake employment verification letter: edited versus generated files, the tells that fail, and six checks on the file.
Spot a fake mortgage statement by confirming principal, amount due, due date, and rate with the current servicer.
Spot a fake W-9 by matching the line 1 name and TIN. The IRS publishes a blank form and does not seal a completed one.
Spot a fake merchant statement by rebuilding amount processed from the fee lines and confirming the merchant ID with the processor.
Spot a fake DBA certificate in the county index: file number, registrant, and expiration. A filing is not good standing.
Spot a fake board resolution by checking that the certifier is not the empowered signer and that the resolution date comes first.
Spot a fake certificate of incumbency by checking the certifier and the state's officer list. A seal does not prove the offices.
How to spot a fake brokerage statement used as proof of assets, and why file history beats a clean layout.
How to spot fake articles of organization by matching the file number and filing receipt to the state record before the account opens.
A wire confirmation is a claim that money moved. Edited and generated payment advice fail file checks. The posted credit is the proof.
How to spot a fake bank reference letter: the relationship claim, the signatory, and the edit history. Letterhead is cheap to copy.
How to spot a fake operating agreement in KYB: edited member schedules, swapped signature pages, and ownership that does not match the file.
Spot a fake certificate of good standing by checking the as-of date, file number, and post-download edits.
How to spot a fake voided check using file history, routing match, and account control. A VOID mark misses edited and generated files.
Verification reads the page and matches the applicant. Fraud detection reads the file. What each misses, how to evaluate each, and when you need both.
PDF metadata analysis for fraud detection: Info dictionary, XMP, timestamps, producer strings, incremental updates, and what each can and cannot prove.
How to spot fake financial statements in SMB lending and KYB: inflated revenue, fake auditor letters, 4506-C and bank reconciliation, six file checks.
How to spot a fake certificate of insurance: why an ACORD 25 confers no rights, the tells that survive, carrier and NAIC lookups, and the six file checks.
How to spot a fake lease agreement in KYC, mortgage, and KYB review: landlord, date, rent, and disclosure tells, plus the six file checks that settle it.
How to spot a fake proof of funds letter in lending, real estate, and escrow: the tells that work, the six file checks, and how to verify with the bank.
How to spot a fake EIN confirmation letter: what a real CP 575 or 147C contains, the tells that survive, IRS TIN Matching limits, and the six file checks.
How lenders and onboarding teams spot fake 1040s, W-2s, and IRS transcripts: line-item tells, edited vs generated files, and the Form 4506-C break-test.
How to spot a fake invoice in factoring, trade finance, and AP: the tells that still work, the six file checks, and the debtor break-test that settles it.
Should compliance teams accept screenshots of bank statements? What a flattened PDF loses, which fraud checks still work on images, and how to set policy.
Explainable document forensics shows where a file was altered, what it said before, and how the examiner knows. Why a fraud score alone fails audit.
How KYC, KYB, rental, and lending teams spot fake utility bills used as proof of address: edited vs generated files, tells that work, six file checks.
How fake document templates and template farms work, why template-made files have no issuance history, and how to detect them in KYC and lending.
Serial document reuse detection catches one statement, stub, or ID recycled across unrelated applicants. Why single-file review misses it.
Loan document fraud detection tests bank statements, pay stubs, and tax docs as a package — the red flags underwriters miss on visual review.
KYB document fraud detection checks certificates, registry extracts, and proof of address as files. Visual review misses edited-after-creation PDFs.
Document fraud statistics from FinCEN, FBI IC3, and FTC — and what those figures miss about edited PDFs, counterfeit templates, and file-level detection.
How to spot a fake certificate of incorporation in KYB: registrar mismatch, edited seals, generated COIs, and serial reuse. Visual review is not enough.
How to detect an AI-generated PDF using metadata, empty Producer strings, model artifacts, and the file history visual review misses.
How lenders and onboarding teams spot fake pay stubs: edited vs generated files, deposit cross-checks, and what visual review misses.
How to spot a fake bank statement: edited-after-creation vs generated-from-scratch, which visual tells still work, and how file history exposes forgeries.
Try another keyword or explore a different topic.